Summary
How to afford assisted living without selling the house depends on mixing multiple resources that fit your family's needs and finances. Beyond a home sale, you can tap into equity, rental income, insurance, veterans benefits, and savings to cover care costs while staying the homeowner.
- Reverse mortgages, HELOCs, and home equity loans let you access home value while keeping ownership; consult a financial advisor on repayment terms.
- Rental income from your home can cover a meaningful portion of monthly care costs if demand stays steady in your area.
- Long-term care insurance policies and hybrid life insurance with care riders may cover services; review your policy details and coverage periods carefully.
- Veterans and eligible spouses may qualify for Aid and Attendance pension benefits; a county veterans service officer can guide applications at no cost.
- Combining sources—rental income for expenses, savings for upfront costs, insurance or benefits for gaps—creates a sustainable funding strategy.
Your house holds more than equity. It holds decades of holidays, family photos, and neighbors who know your name, so selling it to pay for assisted living can feel like too much to ask. The good news is that families have options. If you’re wondering how to afford assisted living without selling the house, the answer is usually a mix of resources that fit your finances and what matters most to your family.
How to Afford Assisted Living Without Selling the House: Using Your Home Equity
Your home’s equity can help with financing senior care without selling property. A few options let you tap into it while you stay the owner:
- Reverse mortgages: For homeowners 62 and older, these turn equity into cash through monthly payments or a lump sum. Repayment rules change when the homeowner moves out, so ask a lender how a move to assisted living would affect the loan.
- Home equity lines of credit (HELOCs): A revolving credit line you borrow from as needed, paying interest only on what you use.
- Home equity loans: A one-time lump sum repaid with fixed monthly payments.
These alternatives to selling your home for care work best with a clear repayment plan. A financial advisor can help you weigh the long-term effects of each one.
Renting Out Your Home
Rental income can give you steady money for monthly expenses while you hold on to the house. For many families, it covers a good share of those costs, which makes it one of the more practical ways to keep the house and move to assisted living.
A property management company can take on tenant screening, maintenance calls, and rent collection. This approach tends to work best where rental demand stays steady.
Think through the taxes and upkeep first. Rental income is taxable, and you’ll want reserves set aside for unexpected repairs.
Using Long-Term Care Insurance
If you bought a long-term care policy years ago, now is a good time to read it again. Benefit amounts and coverage periods vary widely, so the details matter.
Look for your policy’s daily benefit amount, elimination period, and how long coverage lasts. Some policies include inflation protection, which raises benefits over time. Your insurance provider can tell you exactly which services are covered and how to file a claim.
If you don’t have a policy, hybrid life insurance with a long-term care rider is another option. It pairs a death benefit with coverage for care.
Exploring Veterans Benefits
Veterans and surviving spouses may qualify for Aid and Attendance, a pension benefit that provides monthly payments to eligible veterans who need help with daily activities. The amount depends on factors like marital status and other income. At Oak Gardens Place, we also offer a Veterans Program with savings for those who served.
Qualification generally includes:
- Meeting minimum military service requirements
- Falling within income and asset limits
- Needing help with daily activities, as shown by medical documentation
Applications can take several months, so it helps to start early. A county veterans service officer can often guide you through the paperwork at no cost. Paired with other resources, these benefits can open up assisted living payment options without a home sale.
Using Savings and Investments
Many families draw on savings, retirement accounts, or investments while keeping the house. Because those funds need to last, a plan matters. A financial planner who focuses on eldercare can help you set up a withdrawal strategy that covers current needs and protects long-term security.
Roth IRA contributions can be withdrawn tax-free at any time. Traditional IRA and 401(k) withdrawals are taxed as income, which affects your budget. Knowing the difference helps you decide which accounts to tap first.
Combining Several Funding Sources
Paying for senior care while keeping the home usually takes more than one source. You might use rental income for monthly expenses and savings for move-in costs, then add veterans benefits or insurance to ease the load on personal assets.
A written plan shows how long each source will last, and regular check-ins keep it in step with changing needs.
Keeping Your Home and Finding the Right Fit
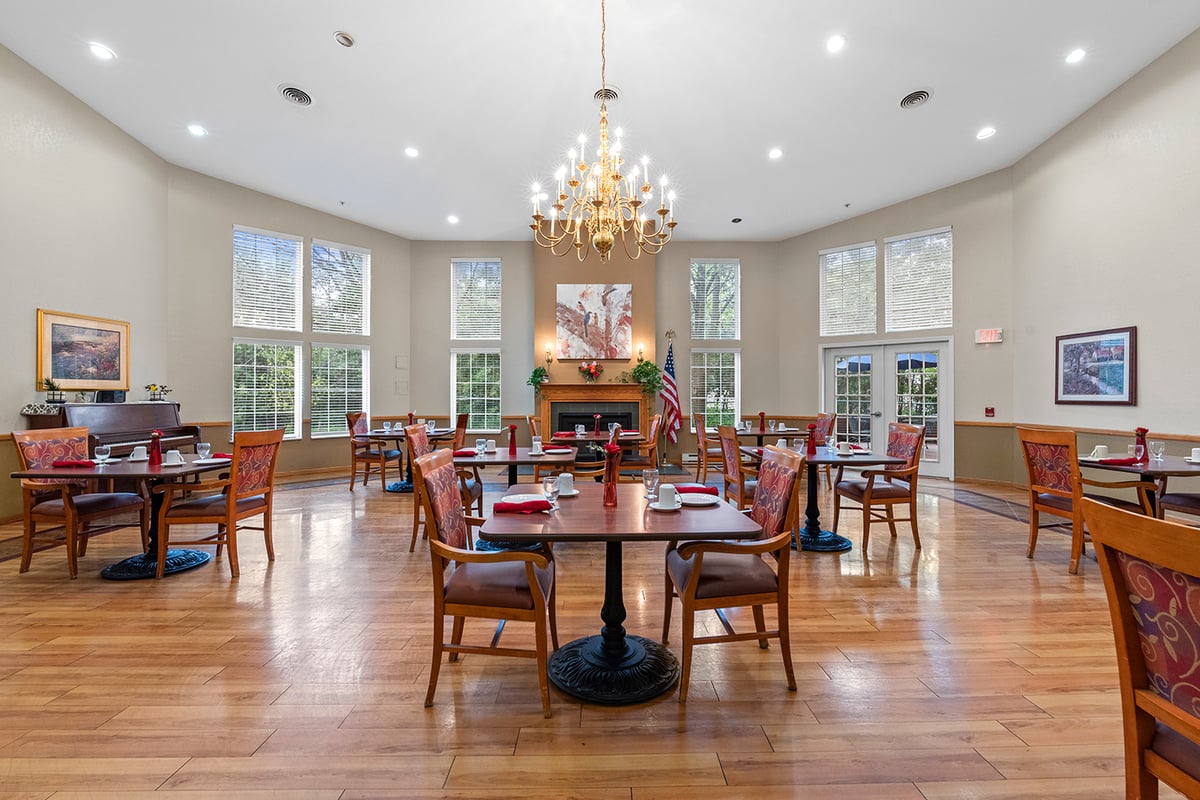
At Oak Gardens Place in Altoona, WI, we're glad to talk through your options and share what we know about paying for assisted living. We want to help your family find a plan that lets you keep the home you cherish. Come meet our neighbors and see the community for yourself, and schedule a tour today.